
Monaco is not a customs third country
The distinction between a yacht’s location and its customs status can have significant consequences, as a recent European court ruling illustrates…
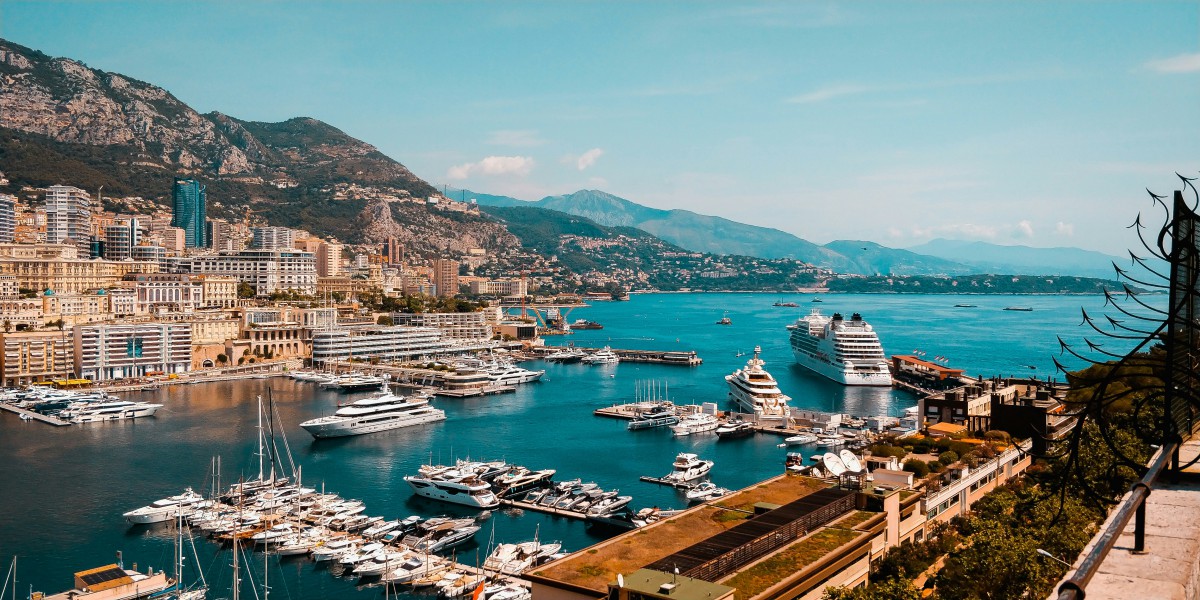
We just guided a similar case. A superyacht based in Monaco is scheduled for a refit at a German shipyard. Its owner lives outside the European Union, the vessel flies a non-EU flag and the management company operates from the Principality. At first glance, the movement may appear to involve the importation of a foreign yacht into the EU, with the corresponding customs and VAT implications.
Yet Monaco occupies a particular position under European law. Although the Principality is an independent state and not a member of the EU, it forms part of the Union’s customs territory and is treated as French territory for VAT purposes. This distinction has existed for decades, but its implications are still easily overlooked when international yacht movements are assessed. The central question is whether the yacht has Union goods status or remains subject to a customs procedure applicable to non-Union goods. The answer may determine whether import duties arise, which formalities apply to a shipyard visit and how the tax consequences of repairs must be assessed.
A judgement delivered by the General Court of the European Union on 21 October 2026, in Case T-383/25, Segelbootwartung, brings these issues into sharper focus.
Monaco’s position under EU customs law
The customs relationship between France and Monaco is rooted in longstanding bilateral arrangements, including the Customs Convention of 18 May 1963. Article 4(2)(a) of the Union Customs Code, Regulation (EU) No 952/2013, expressly includes Monaco within the customs territory of the Union. The VAT treatment follows a similar arrangement. Under Article 7 of Directive 2006/112/EC, transactions originating in or destined for Monaco are treated as transactions originating in or destined for France. Consequently, a yacht that has been duly released for free circulation and retains Union goods status can generally be moved from Monaco to a German shipyard without triggering an importation from a third-country territory.
The position differs from that of a yacht arriving from Switzerland or the United Kingdom, both of which are outside the EU customs territory. This territorial distinction is only the beginning of the analysis. A yacht physically located in Monaco may still qualify as non-Union goods, particularly where it is present under Temporary Admission. Its location within the customs territory does not automatically confer Union goods status. The same principle applies to the vessel’s flag. A Cayman Islands or Marshall Islands registration does not prevent a yacht from acquiring Union goods status following lawful release for free circulation. Equally, a Monaco registration provides no conclusive evidence that such status exists.
A yacht held by a company established outside the EU may nevertheless be Union goods, while a vessel owned through a European structure may remain subject to a special customs procedure. Registration, ownership and customs status must therefore be examined separately.
Ownership adds another layer of complexity. A yacht held by a company established outside the EU may nevertheless be Union goods, while a vessel owned through a European structure may remain subject to a special customs procedure. Registration, ownership and customs status must therefore be examined separately.
Why the distinction matters for refits
The consequences become particularly significant when a yacht enters a shipyard for maintenance, repairs or substantial modification. Where a vessel has Union goods status, its movement within the customs territory generally raises no question of import duties on the hull. The VAT treatment of the shipyard’s services and the supply of equipment remains a separate matter. For non-Union yachts, the position requires closer examination. Temporary Admission allows qualifying vessels to remain in the customs territory under defined conditions, but the permitted use and duration depend on the applicable legal provisions. The familiar 18-month period relates to qualifying privately used sea and inland-waterway vessels.
Commercially used means of transport are governed by separate rules, including time limits linked to their operations. The nature of the proposed work also matters. Routine maintenance and substantial reconstruction may have different customs implications, particularly where new equipment is installed or the vessel’s technical characteristics are materially altered. Inward processing under Article 256 of the Union Customs Code may provide an appropriate framework for repairing or processing non-Union goods without the ordinary import-duty consequences of release for free circulation. Its application requires compliance with the relevant authorisation and procedural conditions.
a refit cannot safely be assessed solely by reference to the yacht’s flag, the owner’s residence or the country in which the shipyard is located.
These distinctions explain why a refit cannot safely be assessed solely by reference to the yacht’s flag, the owner’s residence or the country in which the shipyard is located.
A recent ruling on repairs and import VAT
The General Court’s judgement of 21 October 2026 concerns a sailing boat brought from Switzerland into Germany on a trailer for maintenance and repair work. The Swiss-resident owner failed to present the vessel properly to customs. Following an inspection, the German customs authorities assessed customs duties and import VAT. The boat was subsequently returned to Switzerland after the work had been completed. The dispute eventually reached Germany’s Federal Fiscal Court, which requested a preliminary ruling on the interpretation of EU customs and VAT law. The reference was transferred to the General Court under the revised allocation of jurisdiction for certain preliminary references. The case raised two distinct questions: whether the failure to comply with customs formalities necessarily resulted in import VAT on the vessel and whether the customs debt could be extinguished following its departure from the Union.
The Court’s reasoning is particularly relevant to the treatment of goods brought into the EU exclusively for repair. Under the EU VAT system, import VAT is linked to the entry of goods into the Union’s economic network, where they may become available for consumption. An unlawful introduction into the customs territory can support the presumption that this has occurred, but the circumstances of the particular case may rebut that presumption. In the case before the Court, the sailing boat had been transported on a trailer, had undergone maintenance and repair work and had subsequently been returned to Switzerland without being used as a means of transport within the Union.
The Court distinguished work carried out on a vessel from its actual use as a means of transport. The maintenance and repairs did not, in themselves, establish that the boat had entered the Union’s economic network for consumption. The assessment nevertheless depends on objective and verifiable circumstances, which the national court must establish. The judgement also addresses the extinction of a customs debt under Article 124(1)(k) of the Union Customs Code. That provision allows a debt arising from certain customs infringements to be extinguished where its statutory conditions are satisfied, including that the goods have not been used or consumed and have left the customs territory. The Court held that maintenance and repair work may fall outside the concept of use under Article 124(1)(k), even where inward processing had not been formally authorised.
The location of a vessel and the jurisdiction of its registration are readily identifiable, while its customs status may depend on a history of transactions, movements and procedures extending over several years.
The national court must nevertheless establish whether the work could have qualified for that procedure and whether the relevant authorisation conditions, including those governing retroactive authorisation under Article 211(2) UCC, would have been satisfied. The judgement therefore provides a carefully defined route to the extinction of a customs debt, subject to proof of the statutory requirements and the absence of attempted deception. It does not amount to retrospective authorisation of inward processing or relieve yacht owners of their obligation to comply with customs procedures.
The limits of the judgement for superyachts
The ruling provides useful guidance for yacht owners facing customs assessments following an irregular entry for repair purposes. Its relevance to major superyacht refits, however, must be assessed against the circumstances of each operation. The case concerned a sailing boat transported by road, repaired in Germany and returned to Switzerland without being used for navigation within the EU. A superyacht undertaking sea trials, repositioning voyages or commercial operations during a shipyard period may present materially different facts. Nor does the judgement remove the requirement to select and comply with the appropriate customs procedure before work begins. It provides a legal basis for examining the consequences of an infringement and the possible extinction of a customs debt, subject to the statutory requirements. The VAT treatment of the repair services themselves also remains distinct from import VAT on the vessel. Even where import VAT on the hull does not arise, the shipyard’s services and the supply of equipment must be considered under the applicable VAT rules.
For owners and managers, the evidential position is therefore critical. Import declarations, customs authorisations, records establishing Union goods status, shipyard contracts, technical specifications and transport documents may all be relevant. Where the vessel’s actual movements are in question, logbooks, AIS records and other reliable movement data may help establish the facts. Each document serves a particular purpose, and the legal position depends on the consistency of the overall record.
A yacht’s flag identifies its registry and its home port identifies its location. Its customs status requires a separate legal and evidential assessment.
A question of status, not geography
Monaco illustrates a wider issue in international yacht operations. The location of a vessel and the jurisdiction of its registration are readily identifiable, while its customs status may depend on a history of transactions, movements and procedures extending over several years. The General Court’s recent judgement adds an important distinction between the existence of a customs infringement, the possible extinction of the resulting customs debt and the separate conditions governing import VAT. For a yacht moving from Monaco to a European shipyard, the first question remains whether it has Union goods status or is present under a special customs procedure. Where non-Union goods are involved, the intended work and the applicable customs arrangements must be established before the refit begins. The consequences of getting that assessment wrong can be substantial, particularly when the value of the vessel is measured in tens or hundreds of millions of euros.
A yacht’s flag identifies its registry and its home port identifies its location. Its customs status requires a separate legal and evidential assessment.
As an open-source platform we offer an industry-wide invitation to anyone and everyone in our sector to share their knowledge, experience and opinions. If you have an interesting and valuable contribution to make, and would like to join our growing community of guest columnists, share your ideas with us at newsdesk@thesuperyachtgroup.com
NEW: Sign up for SuperyachtNewsweek!
Get the latest weekly news, in-depth reports, intelligence, and strategic insights, delivered directly from The Superyacht Group's editors and market analysts.
Stay at the forefront of the superyacht industry with SuperyachtNewsweek
Click here to become part of The Superyacht Group community, and join us in our mission to make this industry accessible to all, and prosperous for the long-term. We are offering access to the superyacht industry’s most comprehensive and longstanding archive of business-critical information, as well as a comprehensive, real-time superyacht fleet database, for just £10 per month, because we are One Industry with One Mission. Sign up here.
Related news
The owner asked a simple question and seven reports arrived
An impressive collection of specialists is assembled around the owner. What happens when the question that matters most falls between their responsibilities?
Opinion
The EU reporting rules reshaping private yacht purchases
Why ownership structure and intended use must be settled before completion
Owner
New bill to change navigation in the Balearic Islands
New legislation set to impose 10-knot speed limit one mile from the Balearic coastline
Crew
Italy’s new foreign-flag rule and the EU law question
Italy has introduced a new rule that deserves close attention from owners, managers and advisers working with EU-flagged yachts under 24 metres
Crew
Spain, ‘Golden Visas’ and a warning to every non-EU yacht owner
Spain courted investors with its ‘Golden Visa’. Now, Palma customs is using it to deny Temporary Admission. Miguel Ángel Serra explains
Opinion
Related news
NEW: Sign up for
SuperyachtNewsweek!
Get the latest weekly news, in-depth reports, intelligence, and strategic insights, delivered directly from The Superyacht Group's editors and market analysts.
Stay at the forefront of the superyacht industry with SuperyachtNewsweek